The five things you need to know about the housing market this week.
1. Property values are still drifting downwards
The nationwide median property value fell by 0.3% last month to just over $797,000, the sixth monthly decline in a row and 1.3% lower than a year ago. The figure is also below the previous cycle low recorded in June 2023. Values aren’t plunging, but the slow grind lower is still in progress. Auckland slipped 0.5% in September to $1.021m, while Wellington's median value dropped by 0.7% to $755,115. The median value in Tauranga and Dunedin also fell (-0.3% and -0.1%, respectively), while Hamilton and Christchurch enjoyed lifts of 0.4% and 0.2%.
With economic uncertainty still elevated, mortgage rates rising, and listings abundant (as sales volumes also drift downwards), it’s difficult to see any meaningful rises in property values anytime soon. In fact, further (modest) falls are probably a little more likely.
Start your property search
2. Filled jobs continue to edge higher
That being said, at least one encouraging aspect to all of this is that filled jobs are still showing resilience. Last week, Stats NZ reported a 0.2% monthly rise in August, the third increase in the past four months, which lifted the annual growth rate to 0.9%. Since the trough in October last year, filled jobs have expanded by around 23,200 (although they’re still 35,400 below the peak).
A full-blown labour market recovery may still be a story for 2027, but these latest numbers are a pretty good start. Indeed, most households can probably withstand some increases in mortgage rates, provided that they feel secure in their job or that they could find a new one relatively easily.
3. Dwelling consents march on their merry way
Meanwhile, despite higher mortgage rates and some emerging evidence that house-builders are no longer absorbing increased input costs to the same extent as before, new dwelling consents continue to rise. There were 3440 dwellings approved in August, which was 12% higher than the same month last year, with the 12-month running total now up at almost 41,300 (the highest since August 2023). Now, some of these consents may never turn into actual houses on the ground. But it’s still a remarkably solid recovery and backs up the idea that we might have reached a permanently higher level of new housing supply.
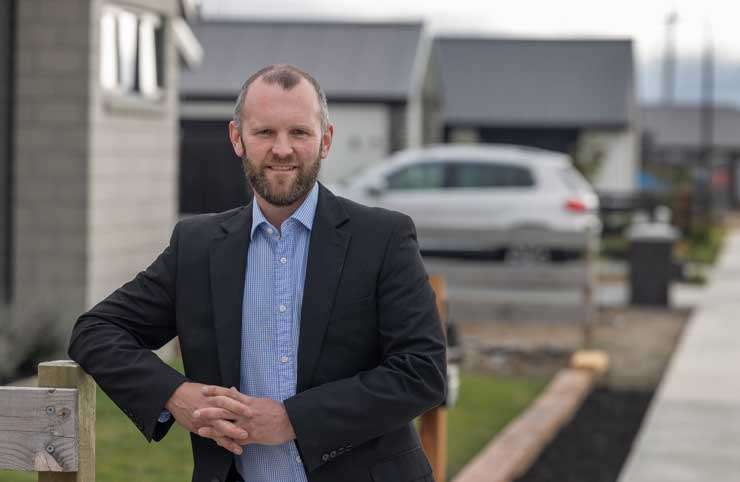
Cotality chief economist Kelvin Davidson: "It’s difficult to see any meaningful rises in property values anytime soon." Photo / Peter Meecham
4. Borrowers are still looking for protection against future rate rises
This week, the Reserve Bank will publish the split of August’s mortgage lending figures by the terms borrowers chose. There’s recently been a shift away from floating rates and short-term fixes and towards longer-term mortgages, such as the two-year rate. This makes sense in an environment where mortgage rates have already been rising and probably have further to go. I’d expect more of the same in the latest data, as people look for some insurance on their future mortgage costs.
5. First-home buyers likely to remain in pole position
The Cotality Buyer Classification figures for September are due this week, and it’s hard to see much changing. I’d expect first-home buyers to retain a strong market share, movers subdued, and mortgaged multiple property owners somewhere in the middle. With investors now having more certainty about the interest deductibility rules, there may be a bit more buying action from this group over the medium term. But plenty of challenges remain, including sluggish rents, higher mortgage rates, and pressure from council rates and home insurance.
- Kelvin Davidson is chief economist at property insights firm Cotality