The five things you need to know about the housing market this week.
1. Mortgage lending activity has cooled again
There was $7.2 billion of gross new mortgage lending in August, not a bad number, but still down by $0.4b from the same month last year; the second decline in a row. Both owner-occupiers and investors have contributed to the slowdown, although a recent uptick in interest-only investor lending is one to watch. Bank switching activity has eased a bit lately, but it’s still quite high.
Meanwhile, the LVR and DTI speed limits are not really being tested, with lower house prices helping to limit loan sizes in relation to the value of the property and to incomes. First-home buyers continue to take advantage of the low-deposit lending allowances, though, with 55% of loans to this group being done at less than 20% equity in August, close to a record high.
Start your property search
2. The clouds clear a little for investors
It had become increasingly obvious over the past few months that some would-be property investors were hanging back because of uncertainty around mortgage interest deductibility and whether or not Labour would phase it out again if elected to government in November. In the event, they’ve announced they wouldn’t change the current system, citing possible complications around pairing any deductibility changes to the introduction of a comprehensive capital gains tax, as well as reluctance to risk a sharp reacceleration in rents.
Putting aside the rights or wrongs, the bottom line is that Labour’s announcement does make things clearer for property investors. But will it drive a marked, new rise in activity? I’m cautious, given that the economic backdrop is still shaky, rents are subdued, interest rates have increased, operating costs are rising (e.g. council rates), and there are also some question marks emerging about long-term capital growth prospects too.
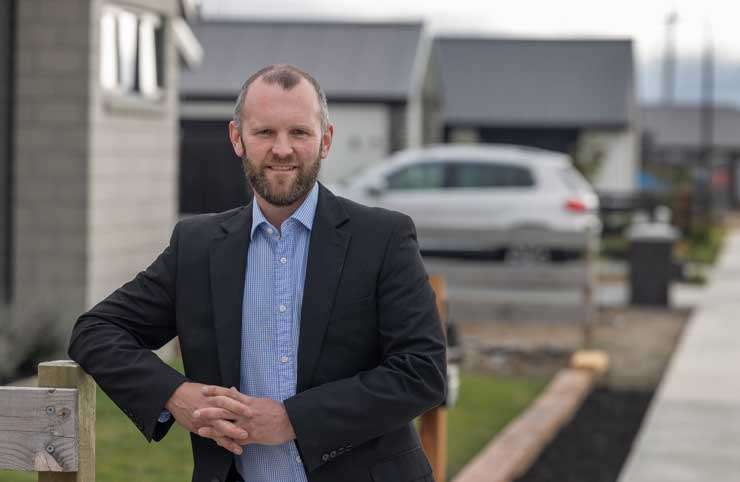
Cotality chief economist Kelvin Davidson: “Putting aside the rights or wrongs, the bottom line is that Labour’s announcement does make things clearer for property investors.” Photo / Peter Meecham
3. The economy isn’t quite back on track yet
Indeed, speaking of the economy, the latest NZ Activity Index (NZAC) from Stats NZ showed a rise of 1.9% in August compared to the same month last year – not a bad result, but amongst the slowest rises we’ve seen in the past 15-18 months. In other words, it backs up what we’re seeing elsewhere too: some good economic results, some a bit softer. At this stage, the economy looks likely to grow again in Q3 (after Q2’s 0.2% lift), but a really strong upturn may still be a story for 2027, not this year.
4. Employment has stabilised but isn’t really growing yet
On Monday this week we’ll get the filled jobs data for August from Stats NZ. Employment has actually been fairly resilient lately as firms “hoard” labour in advance of any eventual economic recovery. Of course, that’s not the same thing as a surge in new job creation, with that firmer upturn perhaps not on the cards until next year. August’s filled jobs may still be relatively flat, helping to explain why the property market is also largely marking time.
5. Is the upturn for dwelling consents about to end?
Then on Thursday Stats NZ will publish data on the number of new dwellings consented in August. The upward trend for these figures has looked pretty firm in recent months, but there’s a question mark about how long this can last. That’s because there’s evidence that builders aren’t absorbing cost rises to the same extent anymore, and mortgage rates have also risen. This may see some households pull back from a new-build commitment.
- Kelvin Davidson is chief economist at property insights firm Cotality