For years, the Bank of Mum and Dad has helped young buyers in New Zealand and Australia get a foot on the property ladder. But now the well is drying up, albeit for very different reasons on either side of the Tasman.
In Australia, a housing downturn has left many parents wary of helping their children buy a home that could soon be worth less than they paid for it.
In New Zealand, meanwhile, easier access to KiwiSaver, low-deposit mortgages, subdued house prices and reduced competition from investors have made it easier for first-home buyers to enter the market without relying on financial help from their parents.
Independent economist Tony Alexander told OneRoof that Australian mortgage brokers had reported growing concern among parents about the risk of negative equity as the housing market undergoes a painful correction.
Start your property search
That contrasts with New Zealand, where house prices have largely tracked sideways for the past three years, and first-home buyers have enjoyed favourable market conditions.
"That situation isn't changing, and it means buyers and their parents don't feel the need to buy as soon as possible."

A growing number of first-home buyers are dipping into their KiwiSaver for a deposit rather than turning to the Bank of Mum and Dad. Photo / Fiona Goodall
Kiwibank chief economist Jarrod Kerr said an increasing number of first-home buyers were using their KiwiSaver for deposits, which was probably why fewer parents were having to dig deep to help.
The Bank of Mum and Dad wasn't completely redundant, but the amounts parents were contributing to deposits had shrunk. “Maybe it’s only $10,000 or $20,000 now, whereas it used to be a significant contributor."
The fact that New Zealand house prices were on average 13% lower than they were at the peak of the market at the start of 2022 and had barely changed in the last three years had made it easier to save for a deposit.
Discover more:
- Mortgagee 'heartbreak': Young couple hit with extra $250k of debt after forced sale
- Real estate's big divide: Whose homes have made $100K a year since the last election?
- Tony Alexander: Where real estate agents are seeing the steepest house price falls
GV Financial Services director Gareth Veale, who is based in Christchurch, said most of his first-home buyer clients could manage a 5% deposit on their own.
“Everyone can come up with 5%. Mum and dad will perhaps top that up a little bit, by giving their kids a gift rather than guaranteeing excessive amounts of lending. Mum and dad aren’t stupid; they'll want to limit their exposure.”
Veale said election promises from both National and Labour would make it even easier for more first-home buyers to get on the property ladder.
National has campaigned on expanding the existing scheme by raising the household/individual income cap to $300,000 (up from the previous caps of $95,000 for single buyers with no dependents and $150,000 for multiple buyers or single buyers with dependents) to help even more couples struggling to scrape together a 20% deposit.
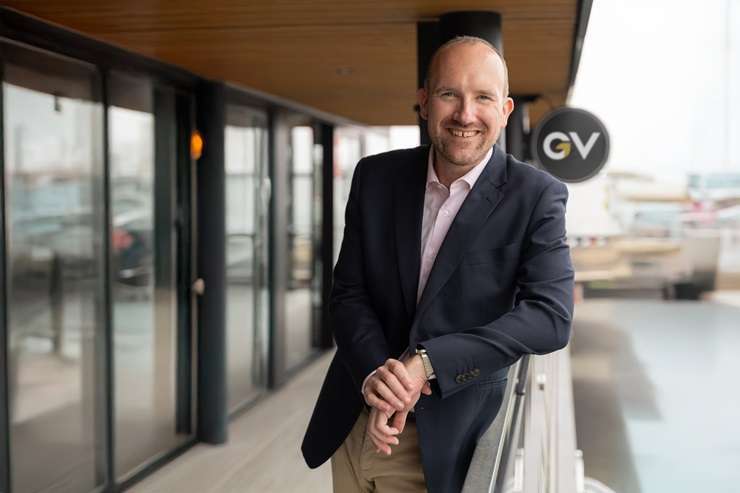
GV Financial Services director Gareth Veale: "Mum and dad aren’t stupid; they'll want to limit their exposure.” Photo / Supplied
Meanwhile, Labour has promised to make employer KiwiSaver contributions compulsory from July 1, 2028 and to lift the minimum employer rate to 6% by 2032.
Float Mortgages financial adviser Geoff Christopher had noticed that parents were increasingly choosing to give their children cash gifts rather than using their homes to guarantee a loan, which he hadn’t seen happen for years.
“There are still a lot of people that get gifts or support from family. Gifting is still a massive part of what is going on.”
Some wealthier parents, who had cash sitting in the bank, were helping their children get the deposit to 20% so they could get the special interest rates; others with equity in their home would borrow the money from their own application and then give that to their children, he said.
“Generally, when parents are trying to help their kids buy a house, they aren’t expecting [the money] back.”
- Click here to find properties for sale