The five things you need to know about the housing market this week.
1. The climate gamble: Flood risks v the housing market
New Cotality research, out last week, shows which areas of the country have the highest flood risks. Wairoa, Buller, Napier, Gore and Westland have the highest concentrations of properties exposed to elevated threats.
In Wairoa, 66% of properties are rated in the higher flood risk categories, followed by Buller (61%), Napier (56%), Gore (50%) and Westland (43%). Christchurch has the largest number of properties in the higher flood risk categories, with around 24,000 homes affected. Napier follows with approximately 13,900, ahead of Auckland City with around 11,300 and Lower Hutt with about 10,400.
Start your property search
At the other end of the scale, many parts of New Zealand remain relatively low risk. In 14 of the 72 districts analysed, at least 90% of properties were classified in the two lowest flood risk categories (with a score of zero or one). But this does not equate to no risk at all.
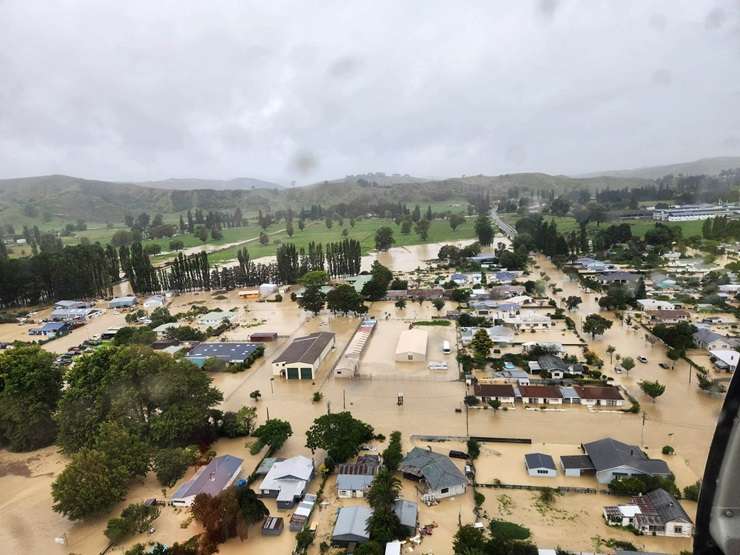
Flooding in Wairoa in 2023 after Cyclone Gabrielle Photo / Supplied
Indeed, all homeowners, regardless of where they live, should be thinking about flood issues and how their insurance premiums might change over time. Granted, that’s a tricky forecast to assess. But that doesn’t make it any less vital.
In terms of what this might mean for property values, it’s not too much of a stretch to suggest that over time a gap will open up between risky and less risky dwellings, although this could take the form of slower growth in risky areas, rather than outright price falls. But with house price growth expected to be lower in future than it’s been in the past, flood risks will become yet another consideration for anybody thinking about buying a property.
2. Property sales continue to decline
Cotality recorded 6621 transactions in October, down by about 26% from the same month last year and the 10th fall in a row. The annual rolling total has now eased down to 85,934 – not horrendous in a long-term context, but still below a more normal figure of at least 90,000 or so, and also not really enough to make a dent in the stock of listings on the market either. Granted, October’s weakness may be related to pre-election uncertainty, so some of the "lost" sales may be recouped in the coming months. But even so, the mood out there still seems very cautious, and it’s hard to see sales volumes lifting sustainably in the next little while.
3. Financial Stability Report: ‘Business as usual’ for the housing market
Meanwhile, given its content, a Financial Stability Report that comes and goes quickly is actually a good thing; if not, we’d probably have a real-world crisis on our hands! That being said, there were still a few things to note from a housing perspective. First, there were no changes to the LVR or DTI rules, and the RBNZ noted that credit availability is not a major constraint, while housing-related financial stability risks also remain contained, including low levels of mortgage stress.
Cotality chief economist Kelvin Davidson: "The mood out there still seems very cautious, and it’s hard to see sales volumes lifting sustainably in the next little while." Photo / Peter Meecham
Second, the current soft patch doesn’t seem likely to end anytime soon. Indeed, the report noted that weak population growth, high ownership costs, and plentiful listings are set to keep house prices subdued in the near term. Development conditions also remain challenging, with weak presales, high construction costs, and some pockets of townhouse stock remaining unsold.
4. Inflation remains a problem
Last week’s selected price indexes data for October from Stats NZ was "middle of the road", with some components still very concerning (e.g. fuel, airfares), but others more contained, such as food and rents. In the end, it probably didn’t alter expectations too much in either direction – inflation’s still a problem and will likely need a higher OCR at some stage, but it’s not necessarily soaring either.
5. Mortgage lending still slowing?
Just a quick look ahead, the RBNZ will publish October’s lending stats on Wednesday this week. Activity has been slowing a bit in recent months and probably did so again in October. As always, I’ll be focusing most on the breakdowns by LVR and DTI (likely still under control), as well as the bank switching/refi activity – which has remained relatively high lately.
- Kelvin Davidson is chief economist at property insights firm Cotality