- Fixed mortgage rates have risen, ending ultra-cheap loans, but experts expect no severe repayment shocks.
- The Reserve Bank plans more rate increases, but economists expect mortgage rises to remain modest.
- Homeowners are favouring one- and two-year fixes, while Christchurch first-home buyers benefit from improved affordability.
The era of ultra-cheap home loans is over, at least for now, but homeowners locking in a mortgage today are unlikely to face much pain, experts say.
Start your property search
Fixed mortgage rates have been creeping up since the start of this year, as banks respond to rising inflation and instability in the global economy.
The one-year home loan rate has jumped from the low fours to the mid-fives, while the best five-year rate has risen from 4.99% to 5.49%, although some banks have pushed it above 6%.
The Reserve Bank of New Zealand has raised the Official Cash Rate from 2.25% to 2.75% and plans more hikes as it moves the rate above 3% by early 2027.
But even though home loans have become more expensive this year, economists told OneRoof that the nasty interest rate shocks of 2023 and 2024 – when some homeowners saw rising interest rates add hundreds of dollars to their monthly mortgage bill – are unlikely to be repeated.
Kiwibank chief economist Jarrod Kerr said mortgage rates were “pretty neutral” right now and he didn’t expect them to move much higher from the early 5%s for some time.
He said many homeowners who fixed at the end of last year did so for two to three years.
“Households are smart when it comes to this stuff. They were taking the punt on the way down, which paid off because they were rolling off every six months onto lower rates. And then, once the bottom was declared, they started fixing for two or three years, so those rates were really moving. I think a lot of people have gone out to 2028 / 2029.”
Discover more:
- Plaster home in double grammar zone sparks 220-bid auction frenzy
- Tony Alexander: Where house prices will rise first and why
- Homeowner fights back tears after house sells for life-changing sum
Opes Partners economist Ed McKnight agreed that the lowest interest rates of the current cycle are likely behind us. However, he said any further increases are expected to be modest rather than severe.
“ANZ reckons that by early next year that two-year rate is actually going to fall from about 5.5% to about 5.2% – that’s what they’ve currently got in their forecast.”
McKnight urged those weighing up whether to lock in for one or two years to crunch the numbers first. Locking in a one-year rate of 4.8% versus a two-year rate of 5.2% made sense, he said, provided the gut feeling was that the one-year rate would not jump to more than 5.6% in the next 12 months.
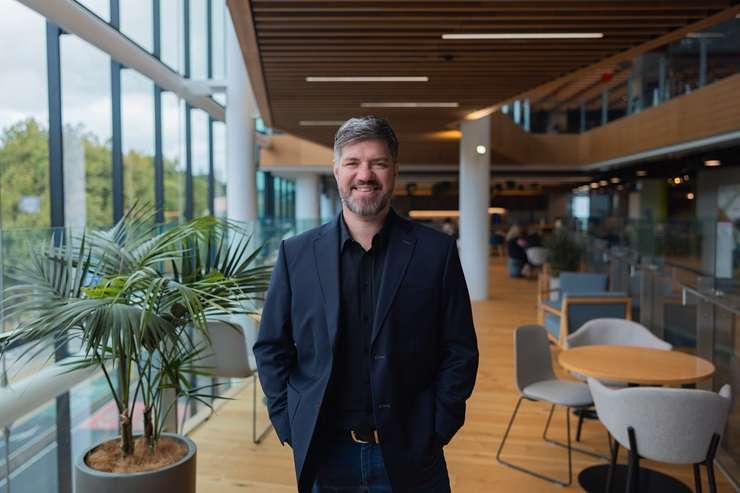
Kiwibank chief economist Jarrod Kerr expects home loan rates to hover around 5% for some time. Photo / Supplied
Loan Market central director and mortgage adviser Cameron Marcroft said the one- and two-year rates were the most popular with clients at the moment, adding that he usually advised people to grab three-year rates when they were in the 4%s. The current three-year rate is hovering around mid-5%s, so it was less appetising.
“In the pundit’s eyes, they feel like it’s probably gone up, but when you compare it, it actually hasn’t gone up that much yet, even after the recent OCR announcement.”
Marcroft expects interest rates to lift a bit more, but said it would more likely impact people’s extra spending money than cause financial hardship.
“Definitely we’ve got a bit more climbing to do, but we’re not going to get into some ugly rates that are going to cripple the country.”
Squirrel South Island managing adviser Nathan Miglani said the current interest rate rises added around $25 to $30 a week to the cost of a typical home loan.
“It’s not ridiculous. No one is in mortgage stress at the moment,” he said, adding that most of their clients were signing up to the cheaper one to two years because it was an easier pill to swallow.
“When we are starting to lock in three-year rates – it’s in the mid-5%s, and it just comes down to affordability.”
Miglani said fewer investors competing for property had helped first-home buyers gain a foothold in the market. July was his office’s busiest month of the year, with 94 properties settling, almost half involving first-home buyers.
- Click here to find properties for sale