The five things you need to know about the housing market this week.
1. A painful time to be a reseller
Amidst all of the post-match election analysis last week (which I’m not going to extend), we published the latest Cotality Pain & Gain Report, which looks at property resales and whether the owners got a price higher or lower than they originally paid. Unsurprisingly in this sluggish market, resellers are generally faring worse than before, with only 84% seeing a gain, down from the figure of 87% three months ago, and the late 2021 peak of more than 99%. The median gain on any profit-making resales was also down, although at $270,000 is still quite significant.
Apartments continued to record the weakest outcomes, with almost half of apartment resales in Q3 making a loss. It's worth noting that the typical loss for an apartment - around $60,000 - is not materially different from other property types. It’s also just a sign of the times. Apartments tend to deliver less price growth than other property types over time, so are always a little more vulnerable to losses.
Start your property search
Auckland and Wellington recorded the weakest resale performance among the main centres. In Auckland, 25.5% of properties were resold for a loss in Q3, followed by Wellington at 20.4%, Hamilton at 19.1%, Tauranga at 15.3%, Christchurch at 7.5% and Dunedin at 6.9%.
Hold period remains vital, with short ownership periods of 4-5 years much more likely to make a gross loss at resale, especially since a lot of those properties would have been purchased at the peak of the market in late 2021 or early 2022. Overall, though, there’s no sign of a fresh collapse or panic in the data. Instead, it’s just a sign of the times – property values have already dropped in many areas, and as the months pass, more vendors just have to face the reality that they’ll be selling into a softer market where buyers have a lot of the bargaining power.
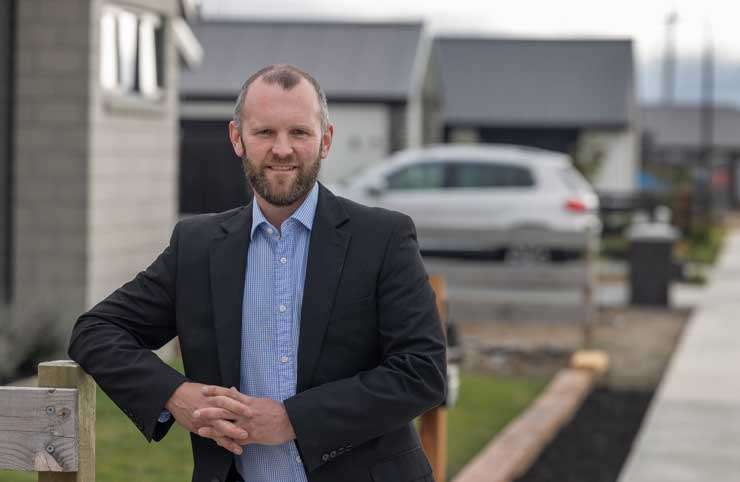
Cotality chief economist Kelvin Davidson: "Apartments tend to deliver less price growth than other property types over time, so are always a little more vulnerable to losses." Photo / Peter Meecham
2. Migration continues to edge higher
On the back of rising new (non-citizen) migrant arrivals to New Zealand, our rolling 12-month net balance increased to 22,612 in September, the highest level since December 2024 – but still below the long term average of around 30,000. In other words, we’re slowly returning closer to normal in terms of our net migration flows, but we’re not quite there yet, and beneath the surface there’s still a lot of NZ citizens departing too. There are hints this migration growth is feeding into rents to some extent, but not significantly yet.
3. Contrasting fortunes for retailers and manufacturers
There was more patchiness in the economic data last week, with electronic card sales from Stats NZ showing another fall in October (even though they’re not inflation-adjusted and we know that the prices of many retail goods, especially fuel, are still rising), but the BNZ-BusinessNZ Manufacturing PMI holding above the rise/fall mark of 50 in October for the 16th month in a row. It’s just a good illustration of the uncertainty that’s out there right now, with some areas going well, and others not.
4. Back on inflation watch again
Looking ahead, on Tuesday this week Stats NZ will publish October’s selected price indexes figures, which cover about 45% of the benchmark quarterly CPI. Although the figures do relate to some of the more volatile inflation elements, such as food and fuel, this release will still be very closely watched, as a guide to how price pressures were unfolding early in the fourth quarter – and keep in mind the Monetary Policy Committee has already set out their expectation that headline CPI could rise from 3.7% in Q3 to 4.4% in Q4. After the recent, softer labour market figures – which reduced the chances of an OCR rise on 9th December – a ‘shock’ upwards result for October prices may tend to push back in the other direction again.
5. No changes expected to the LVR or DTI rules
Just prior to the inflation figures, Tuesday morning will also see the Reserve Bank publish the latest six-monthly Financial Stability Report. This is sometimes used as a way to announce changes to the mortgage lending rules such as LVRs or DTIs, but it seems very unlikely this time around. Meanwhile, the report will probably also indicate that house prices remain in the sustainable range after many years of being too high and relatively unaffordable.
- Kelvin Davidson is chief economist at property insights firm Cotality